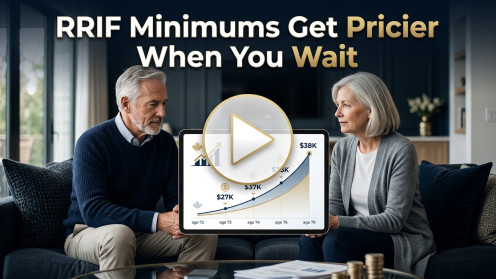
A common question I hear: what happens to your RRSP when you turn 71? In Canada, your RRSP must be closed by December 31 of the year you turn 71, and it often rolls into a RRIF. From there, you’re required to take out minimum withdrawals each year—these are based on your account’s value at the start of the year and your age. For most, withdrawals start around 5% and can climb to nearly 20% by age 95.
Let’s look at the numbers: If you have a $500,000 RRSP growing at roughly 5% per year, in seven years it could reach about $704,000. At age 72, your minimum withdrawal would jump to nearly $38,000, compared to $27,000 if you’d started earlier. That extra income can push you closer to the OAS recovery tax, which kicks in if your income goes above $95,000 in 2026—and don’t forget about other income streams like CPP, workplace pensions, or investments.
Smart planning makes a real difference. Using lower-income years for partial withdrawals, splitting pension income, setting up your RRIF based on a younger spouse’s age, or making regular TFSA contributions—all can help you manage your tax bill more effectively. Building wealth is important, but so is keeping more of it in your pocket. If you’re not sure where to start, you’re not alone. My job is to make your financial future clear, personalized, and stress-free.
Leave a Reply